CO₂ Mineralisation Chemical Market Growth Driven by Carbon Reduction and Low-Carbon Construction
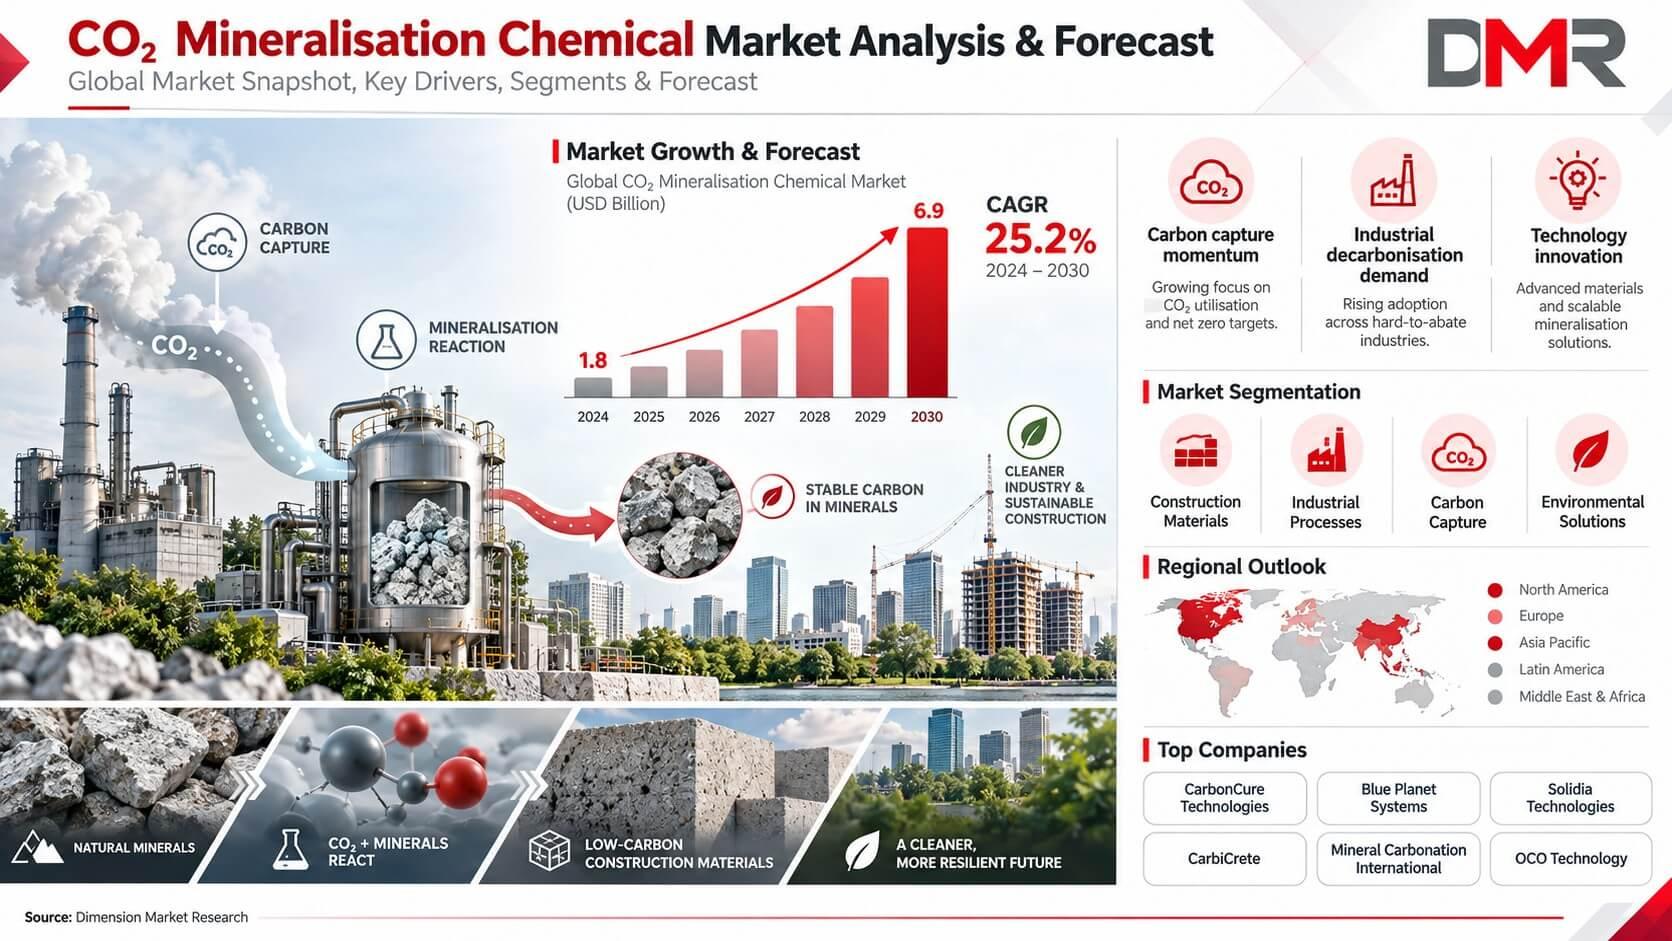
CO₂ Mineralisation Chemical Market to Reach USD 6.9 Billion by 2035, Reports Dimension Market Research
The CO₂ Mineralisation Chemical Market size is projected to grow from USD 1.7 billion in 2026 to USD 6.9 billion by 2035, registering a compound annual growth rate (CAGR) of 17.3% during the forecast period, according to Dimension Market Research. Increasing demand for carbon reduction technologies, industrial decarbonisation, and low-carbon construction materials is supporting market expansion.
Brief Market Overview
CO₂ mineralisation chemicals are materials and chemical inputs used to convert captured carbon dioxide into stable carbonate minerals through reactions with calcium, magnesium, and other alkaline substances. This process supports carbon capture, utilisation and storage (CCUS) strategies by transforming CO₂ into solid mineral forms that can offer long-term storage and commercial value. As industries seek practical pathways to reduce emissions, mineralisation is attracting attention across cement, steel, chemicals, construction, and industrial waste management.
The CO₂ Mineralisation Chemical Market is evolving through direct mineralisation, accelerated carbonation, electrochemical processes, and the use of industrial waste streams as feedstocks. Carbonate materials, including calcium carbonate and magnesium carbonate, offer potential applications in construction products, industrial fillers, and specialty chemicals. Europe is expected to account for 38.0% of the market in 2026, while Asia-Pacific is emerging as an important growth region. Investment in process efficiency, favourable decarbonisation policies, and demand for sustainable materials are expected to shape the market through 2035.
Get free sample of this report (with custom data option): https://dimensionmarketresearch.com/request-sample/co2-mineralisation-chemical-market/
Market Snapshot
- Market size is projected to reach USD 1.7 billion in 2026.
- Market value is forecast to reach USD 6.9 billion by 2035.
- The market is expected to register a 17.3% CAGR from 2026 to 2035.
- Europe is projected to hold a 38.0% market share in 2026.
- Direct mineralisation is expected to account for 46% of the market.
- Industrial waste streams are projected to represent 52% by feedstock source.
- Carbonate materials are expected to account for 49% by product type.
- Industrial emissions are projected to contribute 58% by CO₂ source.
- Construction and infrastructure are expected to account for 44% by end use.
Market Research Findings
The CO₂ Mineralisation Chemical Market report examines the technologies, chemical inputs, feedstocks, and applications shaping the commercial use of mineral carbonation. According to the supplied report estimates, direct mineralisation is projected to lead process segmentation with a 46% share, supported by its suitability for industrial carbon conversion. Industrial waste streams are expected to account for 52% of feedstock demand, reflecting the potential of steel slag, fly ash, cement kiln dust, and mining tailings. Carbonate materials are projected to hold a 49% product share, while construction and infrastructure are expected to represent 44% of end-use demand in 2026. These segments highlight the relationship between permanent carbon storage, waste valorisation, and demand for lower-carbon building materials.
Why Is the CO₂ Mineralisation Chemical Market Growing?
The market is expanding as industrial producers look for ways to address emissions that are difficult to eliminate through electrification and renewable energy alone. Cement, steel, and chemical manufacturing generate substantial process emissions, creating opportunities for mineralisation systems that convert captured CO₂ into stable mineral products.
Regulatory pressure, corporate net-zero commitments, carbon management investments, and the development of low-carbon construction materials are supporting adoption. Mineralisation can also provide a route to recover value from industrial residues rather than treating them solely as waste.
Another important factor is the potential to integrate mineralisation into existing industrial facilities. Using locally available alkaline feedstocks and captured emissions may help reduce transportation requirements and improve process economics. However, commercial viability depends on energy consumption, reaction rates, chemical requirements, feedstock characteristics, and the ability to sell the resulting products.
Key Market Growth Drivers
- Rising demand for industrial carbon reduction and CCUS technologies.
- Growing use of carbonated materials in cement and concrete production.
- Increased interest in converting industrial waste into useful products.
- Stricter emissions policies and corporate net-zero commitments.
- Expanding demand for calcium and magnesium carbonate products.
- Investment in electrochemical and accelerated mineralisation technologies.
- Greater integration of carbon management into industrial operations.
CO₂ Mineralisation Chemical Market Segmentation Analysis
The research scope covers process type, feedstock source, product type, CO₂ source, end-use industry, and regional demand. Three major segments stand out because of their projected shares and commercial relevance.
1. Mineralisation Process Type
Direct mineralisation is projected to account for 46% of the market in 2026. The process converts CO₂ into mineral carbonates through reactions with suitable mineral materials or alkaline substances. Its appeal comes from opportunities to integrate carbon conversion into industrial processes, including cement and steel production.
Indirect mineralisation involves additional processing steps to extract or activate reactive components before carbonation. This approach can be useful when feedstocks have complex compositions or require pretreatment. Accelerated mineralisation, including pressure-enhanced, catalyst-assisted, and electrochemical approaches, is also receiving attention as developers seek faster conversion and improved energy efficiency.
Key areas covered include:
- Direct and indirect mineralisation
- In-situ and ex-situ carbonation
- Gas-solid and aqueous carbonation
- Electrochemical and catalyst-assisted mineralisation
2. Feedstock Source
Industrial waste streams are projected to represent 52% of the market in 2026. Steel slag, fly ash, cement kiln dust, red mud, and mining tailings can contain calcium- or magnesium-bearing compounds that react with CO₂. Their availability creates opportunities to combine emissions management with industrial waste utilisation.
Natural minerals, including olivine, serpentine, basalt, and wollastonite, provide alternative sources for mineral carbonation. Their commercial suitability depends on mineral composition, reactivity, extraction requirements, transportation, and processing costs. Alkaline industrial materials and brines may also support specialised applications.
The report examines:
- Industrial waste streams and natural minerals
- Calcium-based and magnesium-based feedstocks
- Raw material availability and processing requirements
- Opportunities for circular economy integration
Read more about this market: https://dimensionmarketresearch.com/report/co2-mineralisation-chemical-market/
CO₂ Mineralisation Chemical Market Dynamics
Market Trends: Electrochemical Mineralisation and Process Innovation
Electrochemical mineralisation is gaining attention as developers explore electricity-driven methods for converting CO₂ into carbonate products. These approaches may provide opportunities to improve reaction control and integrate mineralisation with renewable electricity. Research is also focusing on catalysts, reactor design, feedstock selection, and process monitoring.
Artificial intelligence can support this work by helping researchers assess material combinations, optimise operating conditions, and analyse reaction performance. However, the commercial benefits depend on validation at industrial scale, energy requirements, and overall production costs.
Market Opportunities: Construction and Industrial Waste Valorisation
Low-carbon construction offers an important opportunity for mineralisation chemicals. Cement and concrete manufacturers can explore carbonated aggregates, mineralised binders, and other products that incorporate captured CO₂. Demand may be supported by infrastructure investment and procurement standards that favour lower-carbon materials.
Industrial waste valorisation provides another opportunity. By processing suitable slags, ash, and mine residues, manufacturers may produce useful mineral materials while reducing waste disposal requirements. Success will depend on consistent feedstock quality, environmental compliance, product certification, and access to customers.
Market Challenges: Capital Costs and Commercial Scalability
High capital expenditure and operating costs remain important barriers to wider deployment. Mineralisation facilities may require specialised reactors, pretreatment equipment, chemical inputs, energy, and emissions monitoring. These requirements can make projects difficult to finance, particularly where industrial operations lack established revenue streams for the resulting products.
Feedstock variability and transportation costs can also affect process performance. Furthermore, mineralisation technologies must demonstrate reliable carbon accounting, product quality, and long-term storage performance. Reducing energy consumption and improving plant utilisation will be important for achieving competitive economics.
Key Competitor Companies
The competitive landscape includes technology developers, construction material producers, carbon capture companies, and mineralisation solution providers.
- CarbonCure Technologies
- Carbfix
- Blue Planet Systems Corporation
- Mineral Carbonation International (MCi)
- Solidia Technologies
- Carbon Upcycling Technologies
- neustark
- CarbiCrete
- CarbonBuilt
- Heidelberg Materials
- Calix Limited
- Carbon Free
- Paebbl
- Carbon8 Systems
- Climeworks
- Heirloom Carbon Technologies
- Lhoist Group
- Green Minerals AS
- Deep Sky
- Fortera
Companies compete through process efficiency, feedstock access, technology development, strategic partnerships, and the commercial scalability of their solutions. Their activities span different parts of the carbon management value chain, and not every listed company is a direct supplier of mineralisation chemicals.
Get 10% instant discount on report purchase
Explore more report:
- Succinic Acid Market
- Stretchable Electronics Market
- Steel Service Centers Market
- Steam Turbine Market
Frequently Asked Questions (FAQs)
1. What is the CO₂ Mineralisation Chemical Market size in 2026?
The market is projected to reach USD 1.7 billion in 2026, according to Dimension Market Research estimates.
2. What is the CO₂ Mineralisation Chemical Market forecast for 2035?
The market is forecast to reach USD 6.9 billion by 2035, reflecting increasing demand for mineralisation solutions.
3. What is the expected CAGR of the CO₂ Mineralisation Chemical Market?
The market is expected to grow at a compound annual growth rate of 17.3% from 2026 to 2035.
4. Which region leads the CO₂ Mineralisation Chemical Market?
Europe is expected to lead the market with a projected 38.0% share in 2026.
5. Which mineralisation process holds the largest market share?
Direct mineralisation is projected to lead process segmentation, accounting for 46% of the market in 2026.
About Us
Dimension Market Research (DMR) is a global market intelligence and consulting firm delivering data-driven insights that help organizations make informed strategic decisions. With expertise across 12+ industries and global markets, DMR provides syndicated reports, custom research, competitive analysis, white space analysis, and business strategy consulting.
Our research solutions combine analytical rigor, industry expertise, and forward-looking intelligence to identify opportunities, reduce risks, and support sustainable growth. Trusted by clients across diverse sectors, DMR is committed to delivering accurate, actionable insights that enable businesses to navigate evolving market landscapes with confidence.
Contact Us
Phone USA: +17323699777
Phone India: +919310023843
E-mail: enquiry@dimensionmarketresearch.com
Address USA: 957 Route 33, Suite 12 #308, Hamilton Square, NJ-08690
Address India: D44, Sector 6, Noida 201301, India

 English